Remembering Lee Kuan Yew - Thank you - The nation with you in your final journey - See u in heaven

Remembering Lee Kuan Yew - Thank you - The nation with you in your final journey - See u in heaven
Presented to you by Property Smart Investor- A Real Estate Online Education and Discussion

Sunday, 30 September 2018

HDB Resale Procedure and Timeline For Buyers and Sellers


New HDB Resale Procedure to be implemented from Jan 1, 2018


From 1 January 2018, resale flat buyers and sellers will need to login to the HDB Resale Portal using their SingPass, to start their buying or selling journey.   

Bought BTO and Resale existing flat
- What constitute a CONTRA when buying a BTO flat and selling the resale flat?
    - There is a CONTRA only when the BTO buyer MUST be taking a HDB loan for the BTO flat
    - The existing Resale flat outstanding loan is HDB loan, not bank loan
    - If the Buyer of BTO flat is not getting a HDB loan (fully funded by bank loan, using the sale of the current resale flat to fund the purchase of BTO or the existing cash and CPF is sufficient to fund the BTO, there is there no contra, that means, the buyer of this resale flat can do enhanced contra

Bought BTO flat, at which point can collect the keys from HDB? 
- When the flat is fully financed  and fully funded. (cash and carry concept)
   - fully funded by bank loan 
   - fullly funded by HDB loan
   - using the sale of the current resale flat to fund the purchase of BTO 
   - the existing cash and CPF is sufficient to fund the BTO
- If there is a shortfall (Eg, 50k), can seek approval to get a temporary loan of 50k from HDB (like a ridging loan)
   - This will help the BTO flat buyer take the key earlier (about 3 months) to do renovation while waiting for the completion of resale flat and hand over the key and no need to ask for extension.
   - From the point of submitting OTP, the temp loan is about 3 months (from OTP resale application to completion)
   - Non concessionary rate, estimation of average of 3 banks rate (generally above 3%)
   - When the BTO flat key is ready, that is the TO flat is comppletely built

MOP: Is based of the date of key collection. Best is to call the Branch Office to confirm

Enhanced Contra Facility. 
Please take note of the following important things when using the Enhanced Contra Facility
- B is the contra party. B buy from A (B's seller) and sell to C (B's buyer).
- Only the contra party (B) can ask for extension of stay from B's buyer (C).
- Both sets of OTPs have to be submitted with 7 calendar days.
- The Contra party (B) cannot have any bank Loan (either existing or the new purchase).
- The contra party (B) can Only use HDB conveyancing lawyers, cannot use any private lawyers.
- The contra party (B) can sell the existing HDB flat and at the same time, buy another resale HDB flat using the Cash Sale Proceeds and refunded CPF monies (without having to wait out for 2 to 3 weeks for the CPF monies to be refunded to the CPF).
- However, the refunded CPF monies cannot be used for the payment of Stamp Duty and Conveyancing fees. but can use the cash Sales Proceeds or Cash out of pocket.

Seller Extension of stay
After Sellers has committed a unit before the OTP of the sale.
Buyer granting Seller extension to stay for a maximum of up to 3 months
Condition
- Only when the seller has already committed a flat because during Resale submission, Resale net will ask to tick YES/NO. If YES, have to key in the address in order to proceed

Before sellera committed a unit
Many agents work around it by keying in NO, get the Resale application submitted first, then when the seller found a place, then they email the form to HDB.

If the Seller have not found or committed a unit upon submitting the sale of the seller's unit
- Still get the buyer and seller to sign the Request for Temporary Extension of Stay by Flat Sellers - Max of 3 months from the date of completion or collection of keys of the sale of the seller's flat
- Selle's Resale Application via Resale Portal, click No Extension to let the submission go through
- After found or committed a unit, Submit Resale application via Resale portal for the purchase
- After the Sales Application and the Purchase Application submitted via Resale net, write a email to the resale officr and attached the Temporary Extension form duly signed by both buyers and seller to HDB resale officer that has been assigned to the case.

For contra cases, Only the contra party can ask for extension. Even contra party don't need extension, the other sellers cannot ask for extension.

New HDB Resale Procedure to be implemented from Jan 1, 2018


Buyer: The portal will guide you through the following steps:-

1.  Register Intent to Buy via HDB Resale Portal 
     - The date of register intent to Buy can be the SAME date of granting of OTP
     - Buyer has to login with their SingPass 
     - Agent (Salesperson) cannot submit on behalf of the buyer
     - Immediately get a completed pdf confirmation after submission
     - Intent to Buy is valid for 12 months
     - It will state the types of grant you are eligible
     - Determine types of CPF Housing grant eligible (grant will be given into CPF money)
      - Once successful, it will reflect as green color and completed

You will receive a following email one month before Intent to sell expires

We noted that you have submitted an 'Intent to Sell' for Blk xxx (Address) on 22 Jun 2020.

Once you have found a buyer, please come back to submit the resale application. If you do not wish to receive further reminders, please login to the HDB Resale Portal and delete the Intent.

Please ignore this email if you have already submitted the resale application or completed the resale transaction.

This is a system-generated email. Should you have any feedback or enquiries, please send to hdbresale@mailbox.hdb.gov.sg.


2.  Choose Mode of Financing (HDB Loan or Bank Loan?)
     - If buyer buying 2nd time HDB, have to use 50% of the cash proceed of the sale in the purchase of the new resale flat.
     - HDB Loan up to 90%. Bank Loan up to 75% with 5% cash (MSR 30%)
     - % of CPF Usage depend on remaining lease of flat and youngest of buyer
     - Remaining lease of flat and youngest age of buyer cannot must be more than 95.
     - Calculator Housing Usage Calculator (since 10/5/2019) or scroll down to see the formular
     - For HDB Loan, need to apply for a valid HLE (Valid for 6 months)
     - HLE stands for HDB Loan Eligibility or Home Loan Eligibility 
     - It will takes 2 weeks to be approved
     - Valid for 6 months
     - Need to have the HLE before Seller can grant you (buyer) the OTP
     - For Bank Loan, need a valid LO before exercising the OTP
     - Can have OTP granted before LO, submit the granted OTP (before exercise) to banks to get the confirmed and valid LO (valid for 2 weeks)
     - LO stands for Letter Of Offer from Bank (Financial Institution) 
     - Get a IPA before searching of flat or before OTP
     - After OTP granted, buyer request for valuation using HDB e-Resale Portal. 
     - Have to provide to the bank the OTP and the Valuation in order to get LO
      - If buyer is below 55, can use all the money in OA or choose to keep up to 20k in OA

3.  Search for Suitable Flat, Negotiate and decide on price with Seller

4.  Get Option to Purchase (OTP) from Seller. Before OTP do take note of the following
     - Important Notes on OTP (Please read through thoroughly)
     - Buyers have 21 days to Exercise OTP. 
     - Whether Sellers or Buyers need to Contra Form 
         - Fill up the 'Application for Enhanced Contra Facility' Form)
     - Whether Sellers requires to Extend to stay after completion. Fill up the Request for Temporary Extention. (Only Contra Party can extend if there are 3 parties. Fill up the Request for Temporary Extension to stay form, Cannot exceed 3 months)


During the 21 days

5.  Decide Mode of Financing
     - For HDB Loan, you must have a valid HLE by now, before Seller grant you OTP 
     - Date of HLE MUST be before Date of OTP
     - For Bank Loan, after Seller grant OTP, together with Valuation, apply to bank to get a Valid LO before you exercise the OTP
     - Date of LO MUST be before the date of Exercising the OTP
     - Send a copy of the OTP (not exercised yet) to the banks

6.  Buyer or Agent (Salesperson) has to Submit Request for Valuation through the HDB e-Resale Portal
      - Valuation is required so long CPF money involved in the purchase
      - Request for Valuation can be submitted after the OTP has been exercised.
      - Request for Valuation can be submitted even after more than 2 days of after granting of OTP so long the valuation report can be out soon enough before LO and before the 21 days to exercise and before the expiry number of days of submission. 
     - The date of register intent to Buy can be the same date of granting of OTP
     - Agent (Salesperson) can submit on behalf of buyer
     - Recommended the with the next working day or within 24 hours after OTP granted (that means can do submission immediately after exercising)
     - OR within the 21 days of Option period. 
     - Recommended to submit soonest because the valuation report needs about 7 days.
     - Terms and Condition for Request For Valuation
     - Login to HDB e-Resale Portal to Apply for HDB Request for Valuation
     - Image or pdf of the 1st page of OTP will do
     - Only detail of 1 seller will do (esp Seller Hp and email so at to be notified)
     - Buyer Hp and email

After valuation request, Salesperson will receive the following email

- Thank you for your request to find out the value which will form the basis for housing loan and CPF usage.
- Once we are ready with the value, we will inform you via email. 
- Buyer(s) may then check the status via the HDB Resale Portal. 
- HDB's letter that informs the buyer of the value will remain available for viewing and download  in the resale portal until 1 month after the resale completion

7.  Received a Valid Valuation Report from HDB
     - Within 2-3 days (HDB will normally state 7 - 10 days)
     - Send a copy of the valuation report to the bank

8.  Exercise OTP within 21 days (after you have HLE/LO and Valuation)

9.  Submit Resale Application after you have exercised the OTP
     - Agent (Salesperson) can submit on behalf of buyer or seller
     - Buyers and Sellers discuss and decide on completion date
     - Either Seller or Buyer can submit 1st, the 2nd party has to submit within 7 days (After 7 days, has to resubmit again)
     - Login to HDB e-Resale Portal to Submit for Resale Application
     - Scroll down to (A) below for all the steps
     - Application of Types of Housing Grant, from CPF board, from 99.co

10. Acknowledge Resale Documents

11. Pay Fees (Online Payment)

12. Endorsement by Seller and Buyer. (After resale submission, within 2 weeks, HDB will send a email to Seller and Buyer to endorse)

13. HDB will send a HDB Technical Inspector to the unit to inspect for
   - Any unauthorized Renovation. (If there is, Seller has to back pay with penalty for the approval for authorized Renovation or reinstate back to original)
   - Casement window with proper rivet
   - Sliding window with Aluminium angle strip installed (only the window facing out, corridor windows don't need, For 3 sets of windows is about $170).
   - Get the HDB approved contractor to do it and get them to fill up the Form B1 and get one of the owner to sign. Then submit to HDB Branch Office via email or in person.

14. Seller Spouse Consent and Resale Portal Endorsement (Simon's case) and print out the payment advice (which completion date has been indicated on the payment advice) to pay the outstanding conservation fee. Need to retain this form and bring down to HDB on completion.
  - (a) Application Form (Request to Process Sale and Purchase of Resale Flat, with Spouse consent at the bottom)
  - (b) Confirmation By Flat Seller 20817I20
  - HDB will update the Resale Portal such that the Sellers need to login to Resale Portal to do Endorsement for the above 2 forms
  - If one Seller is no longer a PR or SC (he/she become a foreigner) and resides oversea (without SingPass), he or agent need to write email to inform HDB and HDB will email the above 2 forms to the Seller (the Endorsement form and the Spouse Consent Form) for him/her to sign and witness by Notary Public in that country. after signing, scan a pdf and email to the Resale Officer, the original copy post to agent or POA to be given to the Resale Officer on Completion date.
  - Only the party without SingPass to access to the Resale portal should go to the Notary Public, don't need both. The party already done the online endorsement don't have to be presence at the Notary Public.
  - (c) Print out the Payment advice to town council to make conservancy payment and bring this on completion day.

15. Only after step 12 and step 13 are done (while step 14 still in progress), then HDB will sent out Approval of Resale and Completion date (usually 1 to 2 weeks after Seller and Buyer endorsement and Form B1 submitted to HDB Branch Office)

Seller to pay HDB lawyer conveyancy fee (Payment of legal advice) via AXS machine before HDB can approve the case

16. To know the completion date, Agent, Seller and Buyer can call HDB Resale Hotline 1800-8663066 by keying in One of the Seller's or Buyer's NRIC number and first 5 digit of the Case Number (will be given during submission to Resale Portal), or Seller and Buyer can login to Resale Portal to check.

17. Wait for Completion letter from HDB Resale (Generally about 7 weeks from Resale Submission. Buyer can login to the resale portal to check. HDB will no longer send letter or email to inform buyer of completion date)

Seller get the HDB approved window contractor to retrofit metal strip for sliding windows and rivet for casement window using HDB B1 form (will be brought down by the contractor and signed by him after fixing, seller has to sign also), then seller will submit this form to BO (in person or via email)

- With the Case Number and one Client (Buyer or Seller) NRIC number, the Agent can call (1800-8663066) find out the completion date and time.

Seller also signed the Window declaration form, download on Resale Portal and bring back on Completion day

Seller also to to Town council to settle final conservancy fee and cancel Giro arrangement, signed by Town Council. bring this form back on completion day.

18. If Seller is oversea, agent can help to arrange HDB Town Council to remove all the items in the flat. To save cost, every month, TC will allow one time removal of 3 bulky items for free. Either put at the corridor or they come in to the house to remove. You can negotiate on the spot and pay them extra to remove all.

19. 1 or 2 days before completion, make appointment with Seller to inspect the house for vacant passion.

20. Completion of Resale and take over of keys at HDB. If buyers use bank loan, the Lawyer can represent you to take over the keys, you don’t need to be presence.
Seller needs settle 2 things
- Buyer buy Fire Insurance if there is a loan
- Buyer apply Utilities transfer
- Window Declaration form signed by Seller
- Payment advice to town council on conservancy (bring on completion day)

Seller's final Sales Cash Proceeds Statement (usually legal fee paid during endorsement)


Procedure to submit Valuation application for BUYER online by Agent 

1) Google for HDB Valuation          
2) Submit Request for Value
Step 1: Type of Requestor
3) I confirm that I am the: Salesperson engaged by the buyer - I Accept
You will also need the following information to complete the form:
  1. Address of the flat
  2. OTP Serial Number, Option Grant Date, Purchase Price, Option Fee
  3. Scanned copy of page 1 of the OTP
    (Need to attach a scanned copy of page 1 of the OTP in the Request for Value)
  4. Flat seller's name, NRIC no., contact numbers and email address
  5. All buyers' names and NRIC no.
  6. Contact details of 1 buyer
  7. Requestor's contact numbers and email address
  8. Name of credit card holder, credit card number and credit expiry date
    (For payment of Request for Value by credit card)
  9. Login with SingPass


4) Login with SingPass
5) Key in Estate Licence number - Continue
Part 1: Flat address
Part 2: OTP Details
Part 3: Details of seller and Buyer
Part 4 Review
Part 5: Online Payment


Procedure to submit Resale application for BUYER online

(A) Procedure to submit resale application for buyer online

      - Click HDB e-Resale Portal (Not HDB Resale Portal - this meant for Buyers and Sellers only)
      - Click Scroll all the way down, click Submit Resale Application

      - Section 1: Terms and Condition
      - Click I am the Saleperson -> Drop down, select Engaged by buyer 
         -> Drop down, select Buying a HDB Flat -> Click I Accept -> Login via SingPass
      - Key in Estate Licence No. -> Continue


Note: You can Click Save as Draft anytime
To Retrieve, follow the above (A) Procedure to login with SingPass,
-> Select Draft Application -> Next

      -PART 1: Flat and OTP Detail 

        -> Key in Flat Address -> Next
        -> OTP Detail -> OTP Serial Number -> Option Grant Date -> Option Exercise Date
        -> Purchase Price -> Option Fee -> Deposit 
        -> Seller 1 Name - NRIC 
        -> Seller 2 Name - NRIC - Next

      - PART 2: Buyer's Particular or Household Particular
        - Buyer 1: Full Name - NRIC - Gender - Citizenship - Nationality - Marital Status - DOB
                       - Ethnic Group - Mobile number - Email Address 
 
                       - (For SPR) Marriage detail (Marriage in Singapore or Oversea) 
                       - (For SPR) - SPR detail - Date Obtain SPR - Re-entry Permit Issue Date 
                       - Permit Expiry Date
                       - Gross Monthly Income - Mailing Address 
        - Buyer 2: Full Name - NRIC - Gender - Citizenship - Nationality - Marital Status
                       - Ethnic Group - DOB
                       - Relationship to Buyer 1
                       - (For SPR) Date Obtain SPR - Re-entry Permit Issue Date - Permit Expiry Date
                       - Gross Monthly Income

                  - Manner of holding HDB (Joint Tenancy/Tenancy-in-common/Sole Owner)
                  - Occupier's Particular   
                       - Full Name - NRIC - Gender - Citizenship - Nationality - Marital Status - DOB
                       - Relationship to Buyer 1 
- Ethnic Group 
                       - (For SPR) Date Obtain SPR - Re-entry Permit Issue Date - Permit Expiry Date
                       - Gross Monthly Income

      - PART 3: Loan & Grant

                     - GRANT
                         - CPF Housing Grant (solely meant for 1st time buyer)
                         - Proximity Grant (Regardless of number of times purchasing Resale Flat, even being SERS, but Only 1 time in the life time, if taken before, don't need to apply)
                     - 1. I have checked that I am eligible and would like to apply for the CPF Housing Grant    (Yes/No)
                     - 
Reasons for not applying housing grant:
                       - The average gross monthly household income is more than S$7,000.
                        - I want to reserve the CPF housing grant for future purchase of resale flat.
                       - I am unable to produce income document proof.

                        - Other reasons
                      - 2. I have checked that I am eligible and would like to apply for the Proximity Housing Grant        (Yes/No)

If NO              - Reasons for not applying proximity housing grant:
                       - I want to reserve my PHG for future purchase of resale flat
                        - I am not staying together/near my parents/ married child/ single child aged 35 or above
                        - Other reasons
IF YES         - Specify which grant:
                       - Proximity Housing Grant for Family
                        - Proximity Housing Grant for Singles
                          - Live together with your parents or married child or single child aged 35 or above 
                             ($15,000)
                          - Live near (within 4 km) your parents or married child or single child aged 35 or above 
                             ($10,000)
                          - Proximity Housing Grant for Joint Singles

                     - HOUSING LOAN
                     - The buyer(s) is/are
                       - taking a housing loan from HDB
                        - taking a housing loan from a financial institution regulated by Monetary Authority of
                          Singapore
                       - not taking a housing loan for this purchase.
      - If taking a bank loan, please ensure the LO is granted before exercising
      - Furnish the following details
         - Date of Issue of LO - Date of Acceptance of LO - Loan Tenure - Loan Amount
         - Bank Corresponding Address

      - PART 4: Declaration

        - 1. Is/Are the buyer(s) applying for the Enhanced Contra Facility?  Yes/No
        - 2. Do you, your co-buyers or occupiers through a nominee or otherwise own or acquire any 
               interest in a private property in Singapore or overseas?             Yes/No
        - 3. Is any of the buyer(s) represented by a Power of Attorney?
        - 4. Is any of the buyer(s) represented by a Donee under a Lasting Power of Attorney?
        - 5. Is any of the buyer(s) represented by a Deputy/Committee appointed under a Court Order?
        - 6. Is/Are the buyer(s) intending to engage HDB's conveyancing service to act in the flat purchase?
              If NO, Provide Law firm detail
              - Name of Law firm - Correspondence Address - Email - Contact
        - 7. Is any buyer an undischarged bankrupt
             (a) buying a resale flat bigger than 5-room or a 3Gen-flat, or
             (b) buying a resale flat with net purchase price of $500,000 and above?
         - 8. Do the buyer(s) agree with any request made by the seller(s) to continue staying in the flat 
                after the resale completion date?           Yes / No / NA

      - PART 5: Review - Print - Agree

      - PART 6: Document Upload
        For Sellers
        - OTP (Exercised)
        - Married Cert (If married)
        - Letter from Solicitor (If acted by pte lawyer)
        - POA, certified true copy by solicitor (if represented by POA)

        For Buyers
        - Married Cert (If married)
        - LO from Bank (If taking Bank Loan)
        - Letter from Solicitor (If acted by pte lawyer)
        - Death Cert of Spouses (If spouses passed on, buyer is widow)
        - Divorce Cert / Decree Nisai (If buyers were divorced)
        - Care and custody Cert (If single parent with child, Divorced)
        - Birth certs of children
        - for Proximity Grant (stay with parents)
          - Parents marriage cert
          - Both parents NRICs
          - Buyer's birth cert with both parent's name
        - POA, certified true copy by solicitor (if represented by POA)

Document(s) Preparation

Flat Address:   _________
Contact number of Buyer:_
Case Number:________


(i) To facilitate the processing of the resale application, below is a list of document(s) that is required. You will need the following softcopy document(s) before proceeding. If you have more than one document to submit, we recommend that you scan multiple pages into a single file and save your file in the Portable Document Format (PDF). For example, if you need to submit 'Letter of Offer from Bank' and 'Power of Attorney', please save the 'Letter of Offer from Bank' in one PDF file and 'Power of Attorney' in another PDF file.
(ii) If the documents are not available now, you may click 'Save as Draft' to save the information you have entered. Once you have prepared the documents, you may retrieve your draft and complete the application for submission.
(iii) To facilitate the preparation of the document(s), you may wish to print a copy of this page.
(iv) If you need any clarification, please email to hdbresale@mailbox.hdb.gov.sg together with a copy of this page.
Document Required (Example, Proximity Grant, Mom Widow)
  1. LETTER OF OFFER FROM BANK/WARRANT TO ACT
  2. LETTER FROM SOLICITOR
  3. IDENTITY CARD(S2107197H)
  4. BIRTH CERTIFICATE
  5. DEATH CERTIFICATE(PARENT)
      - PART 7: Online Payment


Procedure to submit resale application for SELLER online

(A) Procedure to submit resale application for buyer online
      - Click HDB e-Resale Portal (Not HDB Resale Portal - this meant for Buyers and Sellers only)
      - Click Scroll all the way down, click Submit Resale Application

      - Section 1: Terms and Condition
      - Click I am the Saleperson -> Drop down, select Engaged by Seller 
         -> Drop down, select Buying a HDB Flat -> Click I Accept -> Login via SingPass
      - Key in Estate Licence No. -> Continue


Note: You can Click Save as Draft anytime
To Retrieve, follow the above (A) Procedure to login with SingPass,
-> Select Draft Application -> Next


Part 1:

Flat and OTP Details

Part 2:

Sellers' Particulars

Part 3:

Housing Loans

Part 4:

Declarations

Part 5:

Review

Part 6:

Document Upload

Part 7:

Online Payment


      -PART 1: Flat yoo are buying and OTP Detail 

        -> Key in Flat Address -> Next
        -> OTP Detail -> OTP Serial Number -> Option Grant Date -> Option Exercise Date
        -> Purchase Price -> Option Fee -> Deposit -> Seller ful1 name -> NRIC -> Next

      - PART 2: (For Selier) Seller's Particular or   Particular
        - Seller 1: Full Name - NRIC - Citizenship - Nationality - Marital Status
                       - Mobile number - Email Address - Mailing Address 
        - Seller 2: Full Name - NRIC - Gender - Citizenship - Nationality - Marital Status - 
                       - Relationship to Seller 1
                       - Mobile number - Email Address - Mailing Address

Loans (Part 3 of 7)

Part 1:

Flat and OTP Details

Part 2:

Sellers' Particulars

Part 3:

Housing Loans

Part 4:

Declarations

Part 5:

Review

Part 6:

Document Upload

Part 7:

Online Payment

Housing loan


Declarations (Part 4 of 7)

Part 1:

Flat and OTP Details

Part 2:

Sellers' Particulars

Part 3:

Housing Loans

Part 4:

Declarations

Part 5:

Review

Part 6:

Document Upload

Part 7:

Online Payment

Declarations

QUESTION 1

Note: This facility is not applicable if the contra party has a housing loan from a financial institution regulated by Monetary Authority of Singapore.

QUESTION 2

Note: The temporary extension of stay is only for seller(s) who has/have exercised an OTP or signed a Sale and Purchase Agreement to buy a flat/property in Singapore that is ready for occupation. It is subject to the buyer(s)' agreement and HDB's approval.

QUESTION 3

Note: Private Property refers to private residential, commercial (including market/hawker stalls) and industrial properties, both in Singapore and overseas.

QUESTION 4
QUESTION 5
QUESTION 6
QUESTION 7
QUESTION 8
QUESTION 9

Note: This question is only applicable if none of the sellers are Singapore citizens.


Review (Part 5 of 7)


Save Review

Right click - Print - Save as pdf

Upload Documents (Part 6 of 7)


Seller 1

  • XXXXXXXXX
  • SXXXXXX
  1. OPTION TO PURCHASE
  2. POWER OF ATTORNEY

Right click - Print - Save as pdf

Online Payment (Part 7 of 7)


Save Receipt

Right click - Print - Save as pdf


CPF Usage (%) based on Remaining Lease of the flat and youngest of the buyer


Example: Remaining lease = 47 years
Youngest Buyer = 44 year old

Is the remaining lease of the flat last till you reach 95?
Basic Test = Remaining Lease of Flat + Youngest Age of Buyer (should NOT be less than 95) 
                  = 47 + 44 = 91 (< 95)

If less than 95, than apply the following to calculate the CPF % usage

Formula

                         Remaining lease of Flat - 20             47 - 20          27
CPF Usage = --------------------------------------- = --------------- =  ---- = 87%
                       95 - Age of youngest buyer - 20     95 - 44 - 20       31


Enhanced Housing Grant (EHG) for 1st Timer (Up to $80,000 based on salary)
- Replaced Special Housing Grant (SHG)
- Additional Housing Grant (AHG)
- Document to submit (if staying together with 1st generation parents)
   - 1st generation parents NRIC (both parents), if 1 parent passed on, need either the late parent NRIC or death cert. 
   - 1st generation parents wedding cert (to prove relationship). If the 1st generation parent's wedding cert is lost, buyer can go ROM to retrieve or write to HDB the buyer couldn't produce and reason, then HDB will try their best to find alternative way to retrieve, such as write to ROM, based on past HDB records when both parents owned a flat.
   - Buyer Birth cert. If buyer's birth cert reflect both parents names will be even better.
   - Buyer's parents don't have to be present during appointment, but parents need to have singpass and login to resale portal to endorse (the purpose of endorsement is to give permission to stay together and fully aware that they are locked in for the next 5 years). The buyer can help the parents to login and endorse if the buyer has the parent's singpass. If the parents somehow have problems with the singpass, couldn't endorse online, that the parents need to be present during appointment to sign.


- Best submit for application on the same day, if not have to submit both Resale application within 7 calendar days or 1 week
- Only the contra party can ask for extension of stay. If the contra party do not need extension, this privilege can pass on the the seller, but subject to HDB approval.
- If not contra (or manual contra), using CPF refund, the 2nd resale application has to be done 7-10 days after the completion of the 1st case. At the point of submission, the CPF must reflect the amount of money to be used


HDB Home page - E-Services - Buying a Resale flat - Scroll to 

Enquiry on Buyers eligibility under the Ethnic Integration Policy and SPR Quota

- key in necessary - Accept


HDB Home page - Click magnifying glass - At Search bar, key in HDB Map Services - Click on HDB Map Services - On the search bar on the map (Key in Postal code of block you want to know)


Following is the Formula for calculating Buyer's Stamp Duty (BSD) for RESIDENTIAL
- PP/MV ($360,000 or below): BSD = (PP/MV x 2%) - 1,800
- PP/MV ($1,000,000 or below): BSD = (PP/MV x 3%) - 5,400
- PP/MV (More than $1,000,000): BSD = (PP/MV x 4%) - 15,400
(Where PP is Purchased Price or MV is Market Valuation, whichever is HIGHER)

Following is the Formula for calculating Buyer's Stamp Duty (BSD) for COMMERCIAL
- PP/MV ($360,000 or below): BSD = (PP/MV x 2%) - 1,800
- PP/MV (More than $360,000): BSD = (PP/MV x 3%) - 5,400
(Where PP is Purchased Price or MV is Market Valuation, whichever is HIGHER)

BSD for Purchased Price (PP) or Market Value (MV) whichever is higher that is 1.000,000 or BELOW
For example $1,000,000
1st $180,000 x 1% = $1,800
2nd $180,000 x 2% = $2,600
Remaining $640,000 x 3% = $19,200
Total BSD = $24,600

OR using Formula:  BSD = (PP/MV x 3%) - $5,400

BSD for Purchased Price (PP) or Market Value (MV) whichever is higher that is ABOVE 1.000,000
For example $1,500,000
1st $180,000 x 1% = $1,800
2nd $180,000 x 2% = $2,600
Remaining up to 1,000,000 is $640,000 x 3% = $19,200
BSD up to 1M is $24,600
Remaining above 1,000,000 is $500,000 x 4% = $20,000
Total BSD = $44,600

OR using Formula:  BSD = (PP/MV x 4%) - $15,400

where 15,400 = (4% of 1M (40,000) - BSD up to 1M (24,600)

HDB Home Page - e-Services - Selling a Flat - Resale Flat Prices


How to help you to make money and gain practical experience while waiting for results?
1. Shadow me
2. Start to do matching
3. Start to do warm market calling

Following are practical tips

Agent ask Seller and Buyers Questions

1. Do you know of the whole Resale Timeline?
2. Do you know of the whole Resale Process and Procedure?
3. What are the relevant document to be submitted to HDB?
4. Do you know how to use the Resale Portal to submit Resale Application? Do you know how complicated in submitting the Resale Application?
5. 


Agent ask Seller Specific Questions
1. Do you need any extension to stay? How is the procedure for the extension of stay so that HDB will approve and make it legalized?
2. Do you know how much is your Cash Proceeds after selling your house.
3. Do you need to do contra? If yes, do you know how to do contra?
4. Do you know how to plan the timing so that the money after sale can use to purchase a new resale HDB flat?
5. Do you know about the form B1, about unauthorized renovation? About Casement window and Sliding window requirement and when to submit this form?
6. Do you want to sell fast and have control over your asking price as well as negotiation?

Agent ask Buyer Specific Questions
1. What are the various CPF housing grant scheme and which are the scheme are you eligible.
2. What if seller request to you for extension of stay, How is the procedure for the extension of stay?
3. Do you know about the the amount of CPF you can use based on the remaining lease of the flat?
4. Do you know whether to have OTP first to exercise first or to have loan approval first?
5. Why you want to save the 1% in exchange for busyness, sleepless night if make mistake, worrying for things not so sure and not so certain? Leave it to the expert to look for you and guide you every step of the way.

Advantage of Exclusive 
1. The more agents sell for me, the fastest I can sell
2. The more agents sell for me, the highest I can sell
3. My relative, friend who are agents and want to give them a chance to sell.
4. Afraid of giving exclusive especially to the wrong agent, not hardworking, no experience, not reliable. (Give one month exclusive to test or after one month of non exclusive, choose an exclusive agent)


Disadvantage of Exclusive
1. No control over asking price (every agent advertise the lowest in order to capture buyers to response to their ad.
2. No control over negotiation because buyer give the lowest offer to different agent and see whoever has to power to convince the owner to sell.
3. All the non exclusive agents work for buyers, not work for sellers
4. All the non exclusive agents use your house as a show flat to close their own units or swing buyers to other units.
5. Use your house as an advertisement to serve other buyers.
6. No loyalty (or exclusive service to the seller).

How you look out for good agent to short cut rather use your flat to gain insights and experience?
1. Know real data, how many 3 rooms, 4 rooms, 5 rooms left?
2. Which unit just sold, sold at what price?
3. Have many ready buyers on hands and call them back
4. Have already seen almost all the units in the estate.


Practical case study question
Serving HDB bbuyer
V=290k
Sales = 308k
CP: 70kk
SPR (more than 3 years)
Divorce with a child
Earning 6kk non fixed income per month
How much cash does the buyer needs to prepare in order to fun the purchase?

Answer
1) Cash Component
- COV: $18,000
- 5% cash (o 290) because of bank loan: $14,500 (SPR)
Total: $32,500

2) CPF or Cash Components
- Downpayment 20%: $58,000 (20% of 290k)
- BSD: $4,360 (based on $308k)
- ABSD: $15,400 (5% of $308k) (SPR)
- Legal fee: est $2,800
Total: $80,560
Since bbuyer has only 70k in CPF, Cash reuired is $10,560

Total cash at least need to be prepared by buyer is $32,500 + $10,560 = $44,060
Total 45k cash will bbe quite saffe (plus some miscellaneous expenses)


Formula for Buyer's Stamp Duty SSD
$0 to $$360,000: (PP x 2%) - 1,800
$360,001 to $1 Mil: (PP x 3%) - 5,400
$1 Mil and above: (PP x4%) - 15,400

Additional Buyer's Stamp Duty (ABSD)

9th Cooling Measure effective on 16 Dec 2021

ABSD 9th Cooling Measure effective on 16 Dec 2021


Loan To Value (LTV) Ratio


Case Study: Timeline with Enhanced Contra Facility, Request for delay completion


Case Study: Timeline with Enhanced Contra Facility, Request for delay completion and Request for Extension of Stay


Enhanced CPF Housing Grant (EHG) From Sep 2019
= Additional CPF Housing Grant (AHG) + Special CPF Housing Grant (SHG) (before Sep 2019)

Enhanced Housing Grant, Family Housing Grant, Single Housing Grant, Proximity Housing Grant

I made myself this list in 2011 after seeing a list of “HDB flat types & models” that was wrong and incomplete, original author is unknown but it was copied by many blogs. The below list is my original work for publication on www.teoalida.com, do not copy it without my approval!

Flat type abbreviation: STD = Standard, I = Improved, NG = New Generation, S = Simplified, A = Model A. Some people wrongly abbreviate Standard as S instead of STD.

Flat type naming represent approximate size in sqm and number of rooms, NOT the floor plan layout. Do not associate below sample layouts with flat types, other different layouts do exists with same flat type naming.

1960s-1970s flat types (refuse chute in kitchen)
1-Room Emergency (1960-?) – all demolished
2-Room Emergency (1960-?) – demolished except 5 blocks
1-Room Standard (1960-?) – no evidence if it existed, in my opinion should exists
2-Room Standard (1960-1970) – around 41 sqm, one WC/shower (sample floor plan)
3-Room Standard (1960-1970) – around 50-55 sqm, one WC/shower (sample floor plan)
4-Room Standard (1960-1970) – around 70-75 sqm, one WC/shower, sometimes separate (sample floor plan)
1-Room Improved (1966-1978) – supposedly 33 sqm but multiple layouts exists (sample floor plan)
2-Room Improved (1966-1978) – usually 44 sqm, separate WC and shower (sample floor plan)
3-Room Improved (1966-1978) – usually 60 sqm, separate WC and shower (sample floor plan), 3½-Room I Modified 69 sqm
4-Room Improved (1966-1980) – usually 82-84 sqm, separate WC and shower (sample floor plan)
5-Room Standard (1974-1980) – 117-123 sqm, two toilets (sample floor plan)

1970s-1980s flat types (refuse chute in kitchen)
3-Room New Generation (1976-1989) – usually 67 sqm, two toilets, (sample floor plan), 3½-Room NG Modified 82 sqm
4-Room New Generation (1976-1989) – usually 92 sqm, two toilets (sample floor plan)
5-Room Improved (1977-1990s) – usually 121-123 sqm, two toilets (sample floor plan)
3-Room Simplified (1984-1989) – usually 64 sqm, two full-size toilets (sample floor plan)
4-Room Simplified (1984-1989) – Corridor, usually 84 sqm, two full-size toilets (sample floor plan)
4-Room Simplified (1984-1989) – Corner, usually 88 sqm, two full-size toilets

3-Room Model A (1982-1989) – usually 73-75 sqm, two full-size toilets (sample floor plan), 3½-Room A Modified 88-90 sqm, rare
4-Room Model A (1982-1990s) – usually 105 sqm, two full-size toilets (sample floor plan)
5-Room Model A (1982-1985) – usually 135 sqm, two full-size toilets (just few built, replaced by Executive Apartment) (sample floor plan)
5-Room Model A Maisonette (1983-1984) – most 140 sqm, some up to 155 sqm (TWO floors, just few build, replaced by Executive Maisonette) (sample floor plan)
Executive Apartment (1984-1990s) – usually 142-146 sqm (ONE floor) (sample floor plan)
Executive Maisonette (1984-1990s) – most 147 sqm, some up to 160 sqm (TWO floors) (sample floor plan)
Multi-Generation (1987) – 132 sqm / 151-171 sqm, most 166 sqm (ONE floor, 2 entrances) (sample floor plan)
4-Room / 5-Room / Executive “Jumbo” (1992-1996) – around 90-192 sqm (adjoined by HDB, fresh leases), 1 entrance, 2 or 3 full-size toilets.
4-Room / 5-Room / Executive Adjoined Flat (any year) – around 90-175 sqm (adjoined by owners, original leases), 2 entrances unless owner walled one, 2 kitchens unless owner converted one into something else, up to 4 toilets.
(more floor plans)

Early 1990s flat types (centralized refuse chute, no household shelter)
4-Room Model A (1993-1998) – usually 100-108 sqm
5-Room Improved (1993-1998) – usually 120-128 sqm
5-Room Model A (1993-1998) – usually 133-137 sqm
Executive Apartment (1993-1998) – usually 142-150+ sqm (1 floor)
Executive Maisonette (1993-1998) – usually 144-146 sqm, penthouse maisonettes up to 215 sqm (2 floors)
(sample floor plans)

Late 1990s-present flat types (with household shelter)
Studio Apartment – 35 / 45 sq m (2001-present)
2-Room Model A – 45 sq m (2008-present)
2-Room Flexi – 45 sq m (introduced 2015)
3-Room Model A – 60 sq m (2002-2008), 65 sq m (2008-present)
4-Room Model A – 100 sq m (1998-2000), 90 sq m (2000-present)
4-Room Model A2 – 90 sq m (1998-2000), 85 sq m, some 80 sq m (2000-present), only in SERS blocks
5-Room Improved – 120 sq m (1998-2000), 110 sq m (2000- present)
Executive Apartment – 140 sq m (1998-2000), 125 / 130 sq m (2000-2005)
Executive Maisonette – 140 sq m (1998-2000)
3gen flat – 115 sqm (introduced in 2013 BTO, completed 2017), 4 bedrooms, 3 toilets, home ownership restricted for couples + 1 additional family relative
Note: the naming system (Improved / Model A) is no longer used in sales brochures since 1998, but is still displayed in the Resale flat prices.
(sample floor plans)



Monday, 24 September 2018

Private Enclosed Spaces and Private Roof Terraces to be included as GFA


Private Enclosed Spaces and Private Roof Terraces to be included as GFA

24 June 2015
This is with reference to the Urban Redevelopment Authority (URA) guidelines which came into effect from 12th January 2013.
This article aims at new home owners who may not be completely aware of the following guidelines established by the Urban Redevelopment Authority in 2013.

Background:
Private enclosed spaces (PES) and private roof terraces (RTs) are usually found in flats and condominium developments. Located on the first storey or roof level, these spaces are commonly used for outdoor gardens. Similar to balconies these are semi–outdoor spaces that form a part of the private area which are sold to home buyers.
Formerly, private enclosed spaces and private roof terraces were not included in the computation of Gross Floor Area (GFA). This was to encourage developers to build more outdoor spaces so that residents could enjoy light and openness in their apartment.

New Guidelines with effect from 12th January 2013.
1. The URA has reviewed the guidelines and will now count PES and private RTs for non-landed residential developments as part of the bonus GFA capped at 10% above the master plan control.
2. The above revision will prevent excessive provisions of PES and private RTs and hence in turn
there will be no more compromise on communal space. However developers are still given
flexibility to propose various sizes of PES and private RTs in different configurations that best
meet the market demand.
3. Coverings over PES and private RTs are allowed to address the needs of home owners for
protection against killer litter and weather. However, they need to comply with a set of
guidelines to retain a semi-outdoor character to qualify for the bonus GFA scheme. The list can be found on the URA website.
Height of Common wall between two Residential Units with PES
Due to requests received from residents of the 1st storey units to raise the height of PES common wall with their neighboring unit for better privacy, the common wall may be built up to 1.8m high between a paired PES. However the common wall beyond the balcony edge shall be kept to a maximum of 1m high so as to keep PES beyond the balcony edge as an open outdoor space.


Revision to the Balcony Bonus Gross Floor Area (GFA) Scheme for Private Non-landed Residential Developments to Promote Higher Construction Productivity – Changes to Phase Two Conditions


Revision to the Balcony Bonus Gross Floor Area (GFA) Scheme for Private Non-landed Residential Developments to Promote Higher Construction Productivity – Changes to Phase Two Conditions

  Published: 09 December 2014
Circular No : URA/PB/2014/27-DCG, BCA 104.1.2
Our Ref : DC/ADMIN/CIRCULAR/PB_14, BCA ID
Fax : 6227 4792 (URA)
6325 4800 (BCA)

CIRCULAR TO PROFESSIONAL INSTITUTES

Who Should Know:
Building owners, developers, architects and structural engineers

Effective Date: 
With effect from 9 Dec 2014 to 31 Oct 2018

This circular should be read together with the following circulars:
  1. URA’s Circular No: URA/PB/2009/03-DCG dated 29 April 2009 on “Framework for Managing Bonus Gross Floor Area Incentives”, specifically on the overall 10% bonus GFA budget; and
  2. BCA and URA’s Joint Circular No. BCA 104.1.2 URA/PB/2013/10-DCG dated 2 Sep 2013 on “Revision to the Balcony Bonus Gross Floor Area (GFA) Scheme for Private Non-Landed Residential Developments to Promote Higher Construction Productivity".
  1. The revised Balcony Bonus GFA scheme was implemented on 1 Nov 2013 to encourage the industry to adopt more productive construction solutions. It also aimed to reward developers who make the extra effort to strive for higher buildability.
  2. Since its implementation, BCA and URA have received encouraging response in support of the productivity drive. To further raise construction productivity, BCA has amended the Building Control (Buildability) Regulations to require higher minimum Buildable Design Scores as well as mandatory use of drywalls for all internal dry areas and Prefabricated Bathroom Units (PBUs) for selected developments with effect from 1 Nov 2014 (See BCA’s new Circular No. BCA APPBCA-2014-16 dated 31 Oct 2014).  With these changes, BCA and URA are updating the conditions of the scheme with immediate effect.
Revised conditions to make use of the Balcony Bonus GFA Scheme
  1. Private non-landed residential developments (including executive condominiums) and the residential component of mixed-use projects1 can apply for the balcony bonus GFA scheme up to 10%, subject to the revised conditions specified in the table below with immediate effect.

    Previous ConditionsRevised Conditions
    1. At least 65% of the bathrooms are PBUs1. At least 80% of the bathrooms are PBUs
    2. Achieves a buildable design score that is at least 10 pts above the minimum legislated score2. Achieves a buildable design score of at least 
    a) 90 points for GFA ≥ 25,000sqm 
    b) 87 points for 5,000sqm ≤ GFA < 25,000sqm 
    c) 82 points for 2,000sqm ≤ GFA < 5,000sqm
    3. Uses drywalls for all internal dry areas in the developmentSee note below
    Note : The condition for use of drywall for all internal dry areas is no longer required since drywall is already mandated for all non-landed residential developments under the amended Building Control (Buildability) Regulations.
  2. Where balconies are proposed under the scheme, the prevailing standard guidelines for balconies (e.g. perimeter openness, balcony screening requirements, etc.) will still be applicable.  The Balcony Bonus GFA will not form the new prescribed maximum GPR for the site upon redevelopment.
  3. The requirements for approval of the Balcony Bonus GFA under the scheme, the submission and evaluation process, as well as the consequences of non-compliance as stated in the earlier circular released on 2 Sep 2013 (Circular No. BCA 104.1.2 URA/PB/2013/10-DCG) shall remain the same.
Implementation
  1. The revised conditions will supersede the previous conditions under Phase 2 of the Balcony Bonus GFA scheme and will apply to all new applications for private non-landed residential developments (including executive condominiums) and the residential component of mixed-use projects submitted on or after the effective date2. Only formal development applications (excluding Outline Applications) submitted before the effective date2 which have already been granted Provisional Permission or which will result in a Provisional Permission, will not be subject to the revised conditions under Phase 2 of the Balcony Bonus GFA Scheme2.
  2. We would appreciate it if you could convey the contents of this circular to the relevant members of your organisation. If you or your members have any queries concerning this circular, please do not hesitate to contact BCA’s Mr James Lu at Tel: 6325 5091 (email: james_lu@bca.gov.sg) or URA’s DCG Enquiry Line at Tel: 6223 4811 (email: ura_dcd@ura.gov.sg). For your information, the past circulars to the professional institutes are available from our BCA, URA and CORENET websites in the links http://www.bca.gov.sg,  http://www.corenet.gov.sg/einfo/ and http://www.ura.gov.sg .
Thank You. 

ANG LIAN AIK
GROUP DIRECTOR
CONSTRUCTION PRODUCTIVITY CENTRE
BUILDING & CONSTRUCTION AUTHORITY

HAN YONG HOE
GROUP DIRECTOR
DEVELOPMENT CONTROL
URBAN REDEVELOPMENT AUTHORITY
Join URA's mailing list to get the latest updates on current and future plans and developments around Singapore. Click here to subscribe.
 ___________________
1 Applicable to all new building projects with GFA of 2,000m2 or more.
2 Development applications submitted before the effective date resulting in an Advice or Refusal of Written Permission (RWP) will be evaluated based on the revised conditions under Phase 2 of the Balcony Bonus GFA scheme upon resubmission after the Advice or RWP.


Strata void areas in condos: How to avoid ‘paying for air’


Strata void areas in condos: How to avoid ‘paying for air’

JUNE 12, 2018
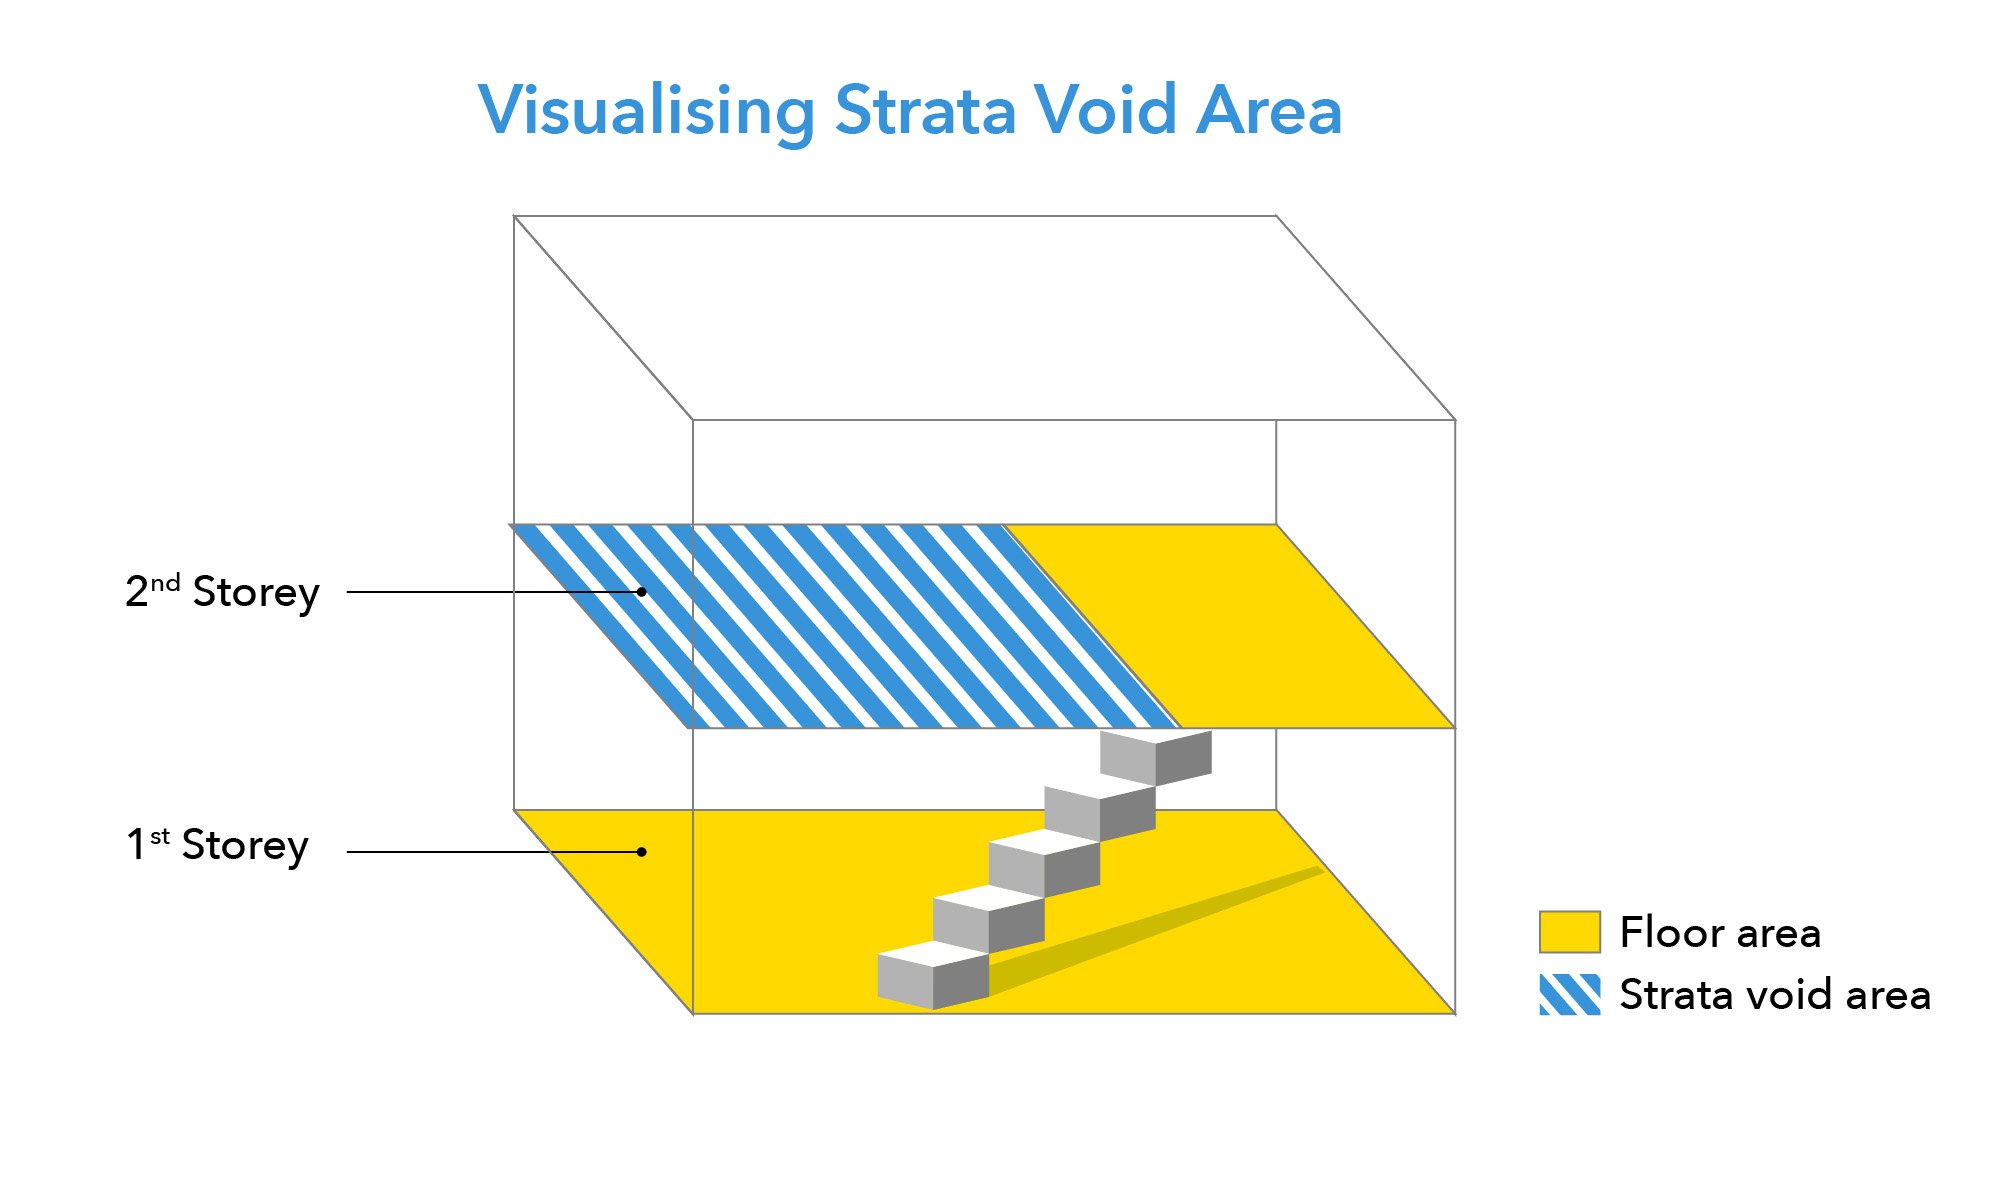
When The Straits Times ran the article Are you ‘paying for air’ when you buy a house? on 11 June 2018, it highlighted an unknowing buyer who was quoted a much higher price than the gross floor area for a new launch condo unit. The article’s intention was to inform buyers of strata void area, which is defined as the void space that is included in the total saleable floor area of the strata unit (e.g. condo unit), as our illustration of a 2-storey unit below shows:
Strata-void-area-diagram
Per square foot, a strata void area may be 30 to 50% the price of actual floor area. This means that a condo unit with strata void area will list a lower psf price than a unit without. This may create some confusion in buyers who don’t immediately discern that a particular unit’s listed psf price is cheaper solely because of its strata void area, example below:
Assuming everything else is the same (e.g. rooms layout, facing, floor),
Unit A: 2,000 sq ft (inclusive of 500 sq ft strata void area) at $1,300 psf priced at (2,000 x $1,300) = $2,600,000
Unit B: 1,500 sq ft (with regular ceiling height throughout) at $1,600 psf priced at (1,500 x $1,600) = $2,400,000
To help buyers identify strata void areas without confusion, we’ve created a simple and straightforward guide. Bookmark this for the next time you’re viewing or buying a property — be it a strata condo or landed unit — so you’ll never be uncertain about “paying for air”.

Do: Pay attention to the floor plan

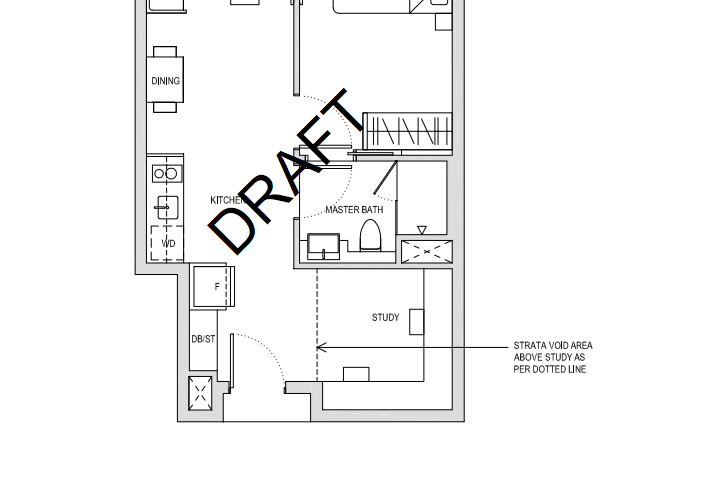
Since 2014, the Urban Redevelopment Authority (URA) has mandated that developers disclose the breakdown of the different areas in the unit, including any strata void areas, in sales documents such as the floor plan.
An example:
Strata Void Area Floor Plan
The strata void area is clearly marked out in this project’s floor plan.
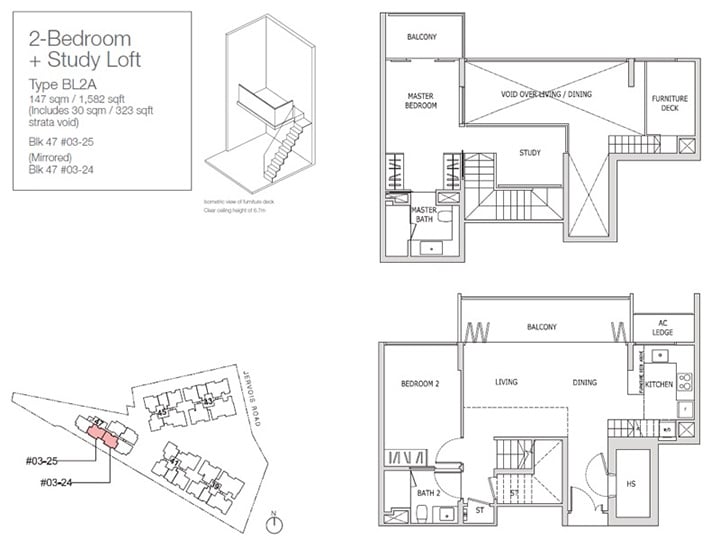
Another example:
Strata Void Area Example 2
The strata void area for this unit is stated in different way. Can you find it?
In other words, developers have an obligation to be transparent to the prospective buyer. Note that although the strata void areas are marked out in the examples above, the prospective buyer should go one step further and clarify the exact boundaries and area of the strata void area with the sales rep.

Do: Read sales documents carefully

Before the buyer pays the booking fee for his desired unit, the developer is required by law to provide him/her with the details of the unit and the housing project, such as the description and estimated areas of all spaces. This includes the void area, if any.
There’s more. The developer must obtain the buyer’s written confirmation of receiving such information. Buyers are understood to have read this information carefully before paying the booking fee.
So, regarding strata void areas, can buyers somehow argue that they were misled in any way? Let’s look back to 2014 when a couple took a executive condominium (EC) developer to court. The couple alleged that the penthouse they paid a $56,050 option fee for was smaller than what they were led to believe.
In its defence, the developer argued that there had been no misrepresentation. This was because the Option to Purchase signed by the couple had clearly stated that the total saleable floor area took into account the air-conditioner ledge, roof terrace and the void area of the unit. The couple eventually dropped the suit.
This case shows that, at the very least, buyers are expected to recognise if any void area is specified on the developer’s sales documents (e.g. Option to Purchase, Sales & Purchase agreement) before they sign. The actual wording might be something like this:
(a) Floor area refers to the estimated area of the whole apartment, inclusive of the area of the air-conditioner ledge and voids (where applicable).
(b) Internal floor area refers to the estimated area of the apartment computed based on the centre line of the apartment wall.

Do: Obtain the necessary certificates (if the property is not a new launch)

If buying a resale condo unit, it might be harder for buyers to notice strata void areas given there might be a lack of documents from the outset. So, buyers should do the following instead before paying the option fee (information courtesy of the Singapore Land Authority, SLA):
Buyers who are buying an uncompleted property in the sub-sale market (i.e. not directly from the developer) should ask the seller for a copy of the Certificate of Strata Area from the seller before paying the option fee. The certificate would state the floor area of the property, including void areas, if any.
Before buying a completed strata unit for which a Subsidiary Strata Certi cate of Title (SSCT) has been issued by SLA, buyers can buy a print-out of the SSCT to check the area of the strata unit and also check if the area of the strata unit includes any Void Areas. For SSCTs issued on or after 1 August 2012, Void Areas, if any, will be shown in the SSCT.
Before buying a completed strata unit, buyers can buy the Strata Certi ed Plan (CPST) for the strata unit from SLA’s Integrated Land Information Service (INLIS) to check if the unit interested in is affected by Void Areas.
If all this sounds complicated to you, that’s the cue for you to engage a CEA-registed Buyer’s Agent to help you with your home-buying journey.

How high must the ceiling be for it to be considered as strata void area?

This is where ambiguity can set in as the practices differ from one developer to another, and from one project to another. Generally, loft units with ceilings that aren’t high enough to allow standing on the loft deck do not count void areas. On the other hand, units with a “double volume” space as part of the strata area, such as a penthouse with a 4.7 metre floor-to-ceiling height, will have void areas factored into the total cost.
An important note for strata landed houses. If there’s an airwell or similar feature, buyers might end up paying for several levels of void areas between the ground floor and the roof.Investors of industrial and commercial spaces should also take note of strata void areas as tenants typically only take floor space into account when renting these spaces.
A good rule of thumb is, if you view a unit and you’re not comfortable when something is classified as a strata void area, just walk away.


Private Enclosed Spaces (PES): Are you paying too much for them?


Private Enclosed Spaces (PES): Are you paying too much for them?

JUNE 10, 2018
A Straits Times report in 2017 revealed that Singapore’s home buyers pay an estimated $780 million for air-con ledges every year. That’s enough money to trade these void spaces for three F-16 fighter jets!
The latest angry buyers are 200 residents in La Fiesta condominium in Sengkang, who have been charged for air-con ledges that are up to five meters long, and take up around nine square meters. That’s the size of a common bedroom in condos nowadays, and buyers are essentially paying for an oversized resting spot for pigeons.
However, it’s not the first time disputes about similar “useless spaces” have occured. Besides air-con ledges, developers have another trick up their sleeve: Private Enclosed Spaces (PES). Here’s what condo buyers need to know about it before they decide to buy a condo unit.

Private Enclosed Spaces (PES) and the Gross Floor Area (GFA) rule: Where is the loophole

The GFA denotes the maximum amount of liveable space a developer can build on a given plot of land.
The Urban Redevelopment Authority (URA) determines what counts as GFA, and what doesn’t. For example, the following Private Enclosed Spaces (PES) do not count as part of the GFA, and hence developers don’t have to worry about them taking up strata space (i.e. space that buyers actually pay for in a condo).
  • Covered link-ways, pavilions, and sheds, such as the gazebo in the communal garden
  • Basement diaphragm walls, which are only important if you don’t want the house to collapse
  • Cladding or curtain walls, a superficial layer that conceals the front of the real thing. Like a fake brick cladding, or Donald Trump’s charity organisation
  • Any leftover space in the carpark, although storage, loading platforms, and lifts still count as part of the GFA.
  • Covered public walkways
  • Covered public concourse
  • Fake roof to conceal unsightly rooftop equipment
  • Utility rooms, such as pump rooms for swimming pools, or chambers for power cables
  • Roof-top or other uncovered landscape gardens, tennis courts, swimming pools
  • Ledges for air conditioners and planters. This is where the above-mentioned problem lies
  • Space for equipment that has to be mounted or permanently put in place, such as a water tower
So air-conditioner ledges are not part of the GFA, which means developers can build them the size of a football field if they want. It still doesn’t take up the spatial limit they have to build more units.
However, as mentioned, developers can charge buyers for the space of the ledge. The reason: air-con ledges solely serve individual units, they are considered part of the strata area, and are therefore chargeable to the buyer. At a price of $900 per square foot, for example, a nine square meter ledge (approx. 97 square feet) will set you back $87,300. That’s pricey for something that holds two air-con compressors and bird poop.

This isn’t the first time we’ve seen this kind of shenanigans though

Back in 2013, the URA had to revise rules regarding Private Enclosed Spaces and private Roof Terraces (RTs). Before that, PES and RTs were not counted as part of the GFA as well.
The result, as you can see in the linked document, was some developers losing their minds and creating giant PESes and RTs. It was good money, because it’s cheaper to build this kind of space than indoor space (just make the top of the unit flat, or throw in a balcony with giant planter boxes, and suddenly the developer makes $150,000 more per sale).
So the URA clamped down on the exploitation of these spaces for profit (with the exception of shared, or communal RTs, which are still not part of the GFA).
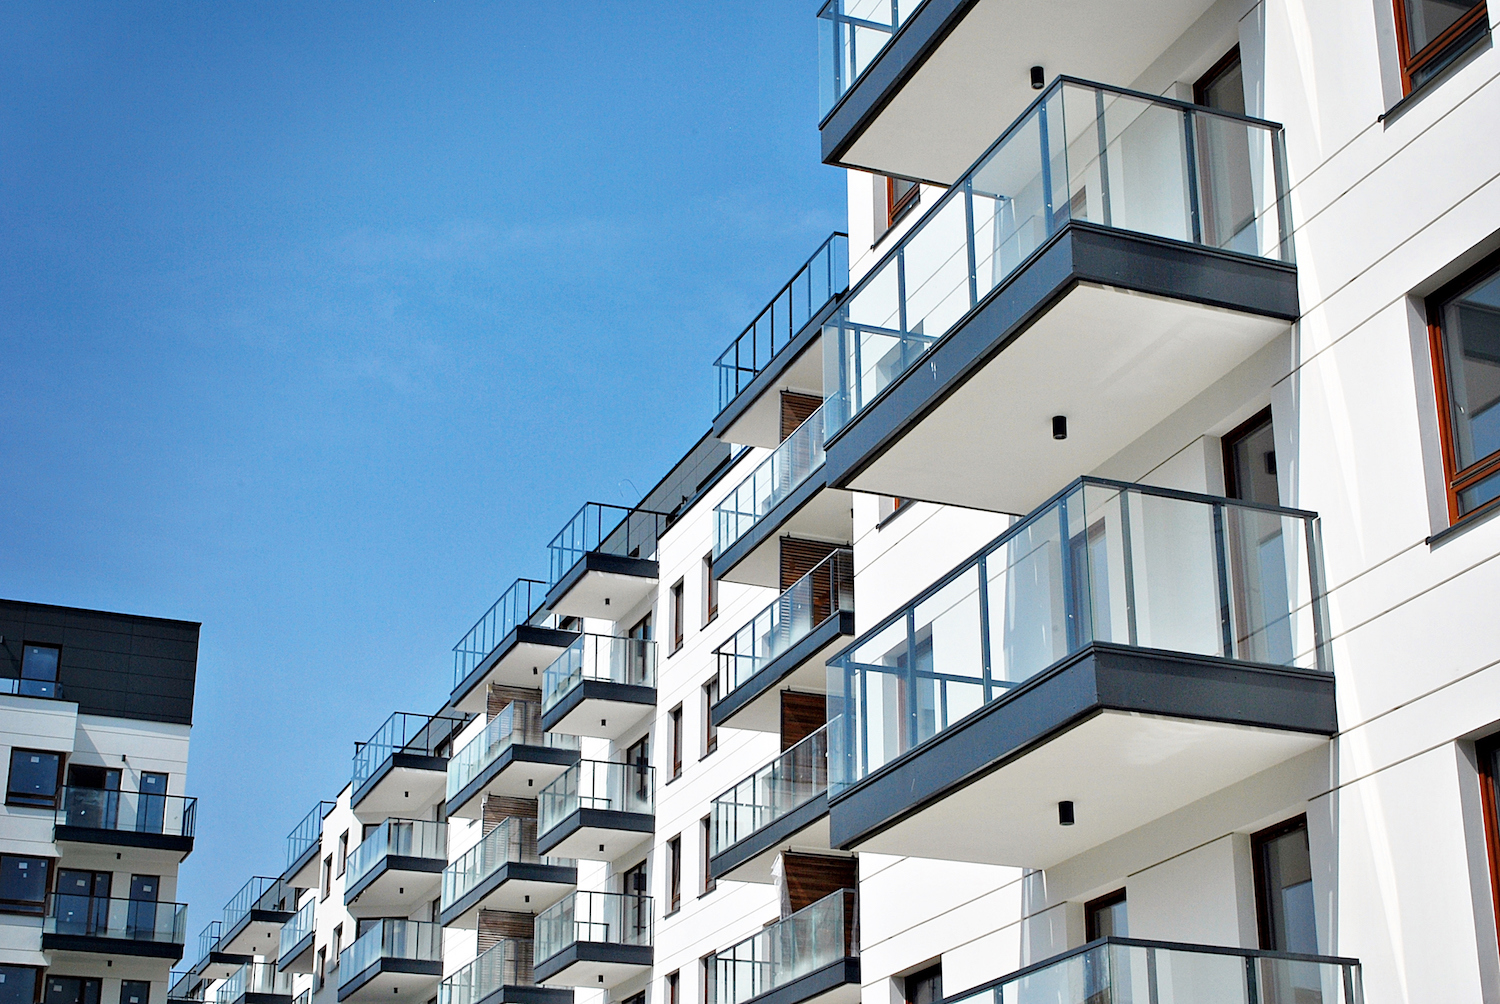
private enclosed space balcony

What about balconies, which counts as GFA?

If you wonder why so many condos have disproportionately oversized balconies when the dining room can barely fit two people and their toy poodle, it’s because URA states that GFA of the balconies “is allowed to be computed over and above the Master Plan control, subject to a cap of 10%.” In layman terms, developers have bonus GFA just for balconies, so they happily build them as part of their units because one, it’s the cheapest part of an apartment block to build and, two, they get to charge you for it.
The truth is, while many buyers love balconies, they half-wish they can switch it to a bigger indoor living area. So to make the best decision when buying a new launch condo, ask yourself whether the balcony is actually laid out in a functional shape and configuration, or if it suits your plans (e.g. the balcony as just a lounge area vs. an entire dining area).

Will we see air-con ledges become part of the GFA?

This may not be as common sense an issue as it seems. You see, including the air-con ledges in the GFA means some* developers might be incentivised to build them as narrow as possible. That’s going to be problematic five to 10 years down the road, when your air-con does break down and you need to find a technician who also doubles as a parkour expert.
What’s probable is that air-con ledges won’t count as part of the GFA, but will remain subject to regulations. For example, URA prescribes that air-con ledges be no wider than a metre, and might in future issue some guidelines on the right size (or range of sizes) for air-con ledges.
(*Not all. High-end developers don’t bother with GFA tricks too often, for the same reason Mercedes won’t use a cheaper car radio to con you out of $50. They’ll tell you that it’s beneath their architects.)

But I don’t want to pay for air-con ledges!

You can’t get out of paying air-con ledges, but you can tell when you’re paying too much. At the condo’s sales office, the developer is required to answer all your questions about which PES or ledge is used for what. While viewing the showflat, also peer out of the windows and yard to see if the air-con ledge, for instance, is clearly represented as per the floor plan.
For the sake of reference, most air-con ledges should be about three to five square meters (approx. 32 to 54 square feet), and will take up to 3% of the total floor space of your unit, no matter its size.


What is Gross Floor Area (GFA), Strata Area, Build-up Area and Build-in Area


What is GFA?

GFA = Land Size (Plot size) x PR (Plot Ratio)

Gross floor area (GFA) measures the bulk and intensity of a development for the purposes of plot ratio control and computation of development charge. Using this GFA concept, the owners or developers are free to determine how much neutral areas they want to provide in their buildings.

All covered floor areas of a building, except otherwise exempted, and uncovered areas for commercial uses are deemed the gross floor area of the building for purposes of plot ratio control and development charge. The gross floor area is the total area of the covered floor space measured between the centre line of party walls, including the thickness of external walls but excluding voids. Accessibility and usability are not criteria for exclusion from GFA

URA Gross Floor Area Handbook
URA Gross Floor Area Handbook PDF

REVISED GROSS FLOOR AREA (GFA) DEFINITION (URA Circular) PDF

GROSS FLOOR AREA (GFA) VERIFICATION SERVICE (URA Circular) PDF


What is Strata Area or Strata Size?

The word Strata means Share. Many strata units sharing the same Land or Plot.
Only for build up blocks like HDB Flat, Condominium, would use Strata Area.

Strata Area = GFA + All the followings

Strata Area is the size of individual units all add up together. This is where the Developer take advantage of the following to made more money and make than enough profit for themselves.

The following are things included in the Strata Area (Size) that was not included in the GFA when developer bought the land from GLS or En-bloc

* Strata Private Void Area

- Strata void areas in condos: How to avoid ‘paying for air’
- Strata void areas graphic illustration by SLA. Making dollars and sense of void areas in a Strata Development. PDF

* Strata Private Balcony Area (Add 10% of GFA)

-  Bonus Balcony Area. Generally about 10% of the GFA
Revision to the Balcony Bonus Gross Floor Area (GFA) Scheme for Private Non-landed Residential Developments to Promote Higher Construction Productivity – Changes to Phase Two Conditions
Strata void areas are getting more rampant in B1 Industry Building and Private Condo

Balcony generally refers to those located in between ground floor and roof terrace.

* Private Enclosed Space (PES)

Private Enclosed Spaces (PES): Are you paying too much for them?
PES normally refers to Ground floor only

* Strata Private Roof Terrace
Roof Terrace generally located at the highest floor or Penthouses

Generally, the PES and the Roof Terrace are Capped at 10% of GFA (Add 10% of GFA)
The URA has reviewed the guidelines and will now count PES and private RTs for non-landed residential developments as part of the bonus GFA capped at 10% above the master plan control.

* Strata Aircon Ledges Area

Setback of RC and Air-Con Ledges for Landed Housing (PDF)

Close loophole that allows developers to charge for space, say buyers and experts


What is Build-Up Area or Build-In Area?

Build-Up Area or Build-In Area normally can be used interchangeabilly. It is used for Landed Properties only.